
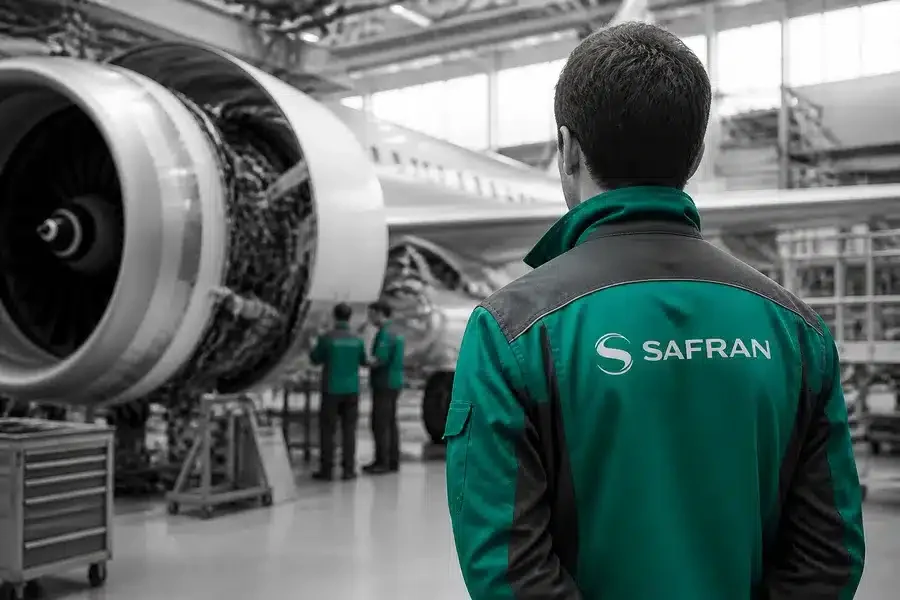
French aerospace supplier Safran (SAF.PA) reported third-quarter sales that edged past analyst expectations on Thursday, reinforcing confidence in sustained commercial aviation demand as the sector recovers.
For long-horizon investors, the modest beat matters less as a quarterly data point and more as evidence that Safran’s core propulsion and equipment businesses are capturing durable volume as airlines continue expanding fleets globally 1.
Key Takeaways
- Safran Q3 sales exceeded analyst consensus, signalling resilient order flow.
- Commercial aviation recovery continues to underpin aerospace supplier revenue.
- Full-year guidance trajectory remains a key watch point for investors.
Market Reaction & Context
Safran’s slight Q3 sales beat positions it favourably among European aerospace peers at a moment when the sector is navigating supply-chain normalisation and rising aircraft deliveries. The result mirrors broader momentum seen across the aerospace and defence supply chain, where demand from airline fleet renewal programmes has supported revenues through 2026 1.
Investors tracking the broader commercial aviation supply chain have also been watching leadership and pipeline stability at major integrators. Concerns around Boeing’s order pipeline durability following a senior sales executive departure highlight how supplier revenues like Safran’s are partly tied to integrator health and programme continuity.
Detailed Analysis
Safran operates across three primary segments: aircraft engines (through CFM International, its joint venture with GE Aerospace), aircraft equipment, and defence. The propulsion business, which supplies the LEAP engine powering Boeing 737 MAX and Airbus A320neo family jets, remains the most significant revenue driver and the segment most sensitive to narrowbody production rates.
A modest beat at the top line in Q3 2026 suggests that LEAP engine deliveries and aftermarket services – which carry higher margins than original equipment – are holding up despite earlier industry concerns about supply constraints on materials and components. Aftermarket revenue, driven by shop visits and spare parts, is particularly important for long-term margin durability because it compounds as the installed engine base grows.
Safran’s equipment and interiors segment, which supplies landing gear, nacelles and aircraft seats, also benefits from the same fleet-expansion cycle. As airlines take delivery of new narrowbody aircraft, demand for both new hardware and subsequent maintenance services increases, creating a multi-year revenue tail that long-horizon investors have come to value in the aerospace supply chain model.
Outlook / Management Quote
Specific management commentary from the Q3 release was not available in detail at time of publication, but Safran’s investor communications have consistently emphasised the visibility provided by long-term engine maintenance contracts. Those agreements, often spanning 10 to 20 years, are a structural feature that distinguishes aerospace suppliers from more cyclical industrials.
“Safran posts slightly higher than expected Q3 sales,” Reuters reported on 23 October 2026, reflecting market recognition that the result modestly exceeded consensus forecasts 1.
Any revision to full-year 2026 guidance – on revenue growth, free cash flow, or adjusted operating income – will be the primary metric investors assess for evidence that Safran’s long-term margin expansion story remains intact.
Conclusion
For retail investors with a multi-year horizon, Safran’s Q3 beat is a constructive signal rather than a transformative catalyst. The more important indicators to watch are the pace of LEAP engine shop visits, the trajectory of narrowbody production rates at Airbus and Boeing, and whether management revises full-year profitability targets upward at its next formal guidance update.
Safran’s combination of original equipment exposure and a growing aftermarket base makes it one of the more defensible positions in European aerospace for investors focused on long-term revenue mix and margin durability.
Not investment advice. For informational purposes only.
References
1(2026, October 23). “Safran posts slightly higher than expected Q3 sales”. Reuters. Retrieved October 23, 2026.